Defense Hypersonic Propulsion and High-Enthalpy Test Infrastructure Awards: Accelerating Flight Readiness in September 2026
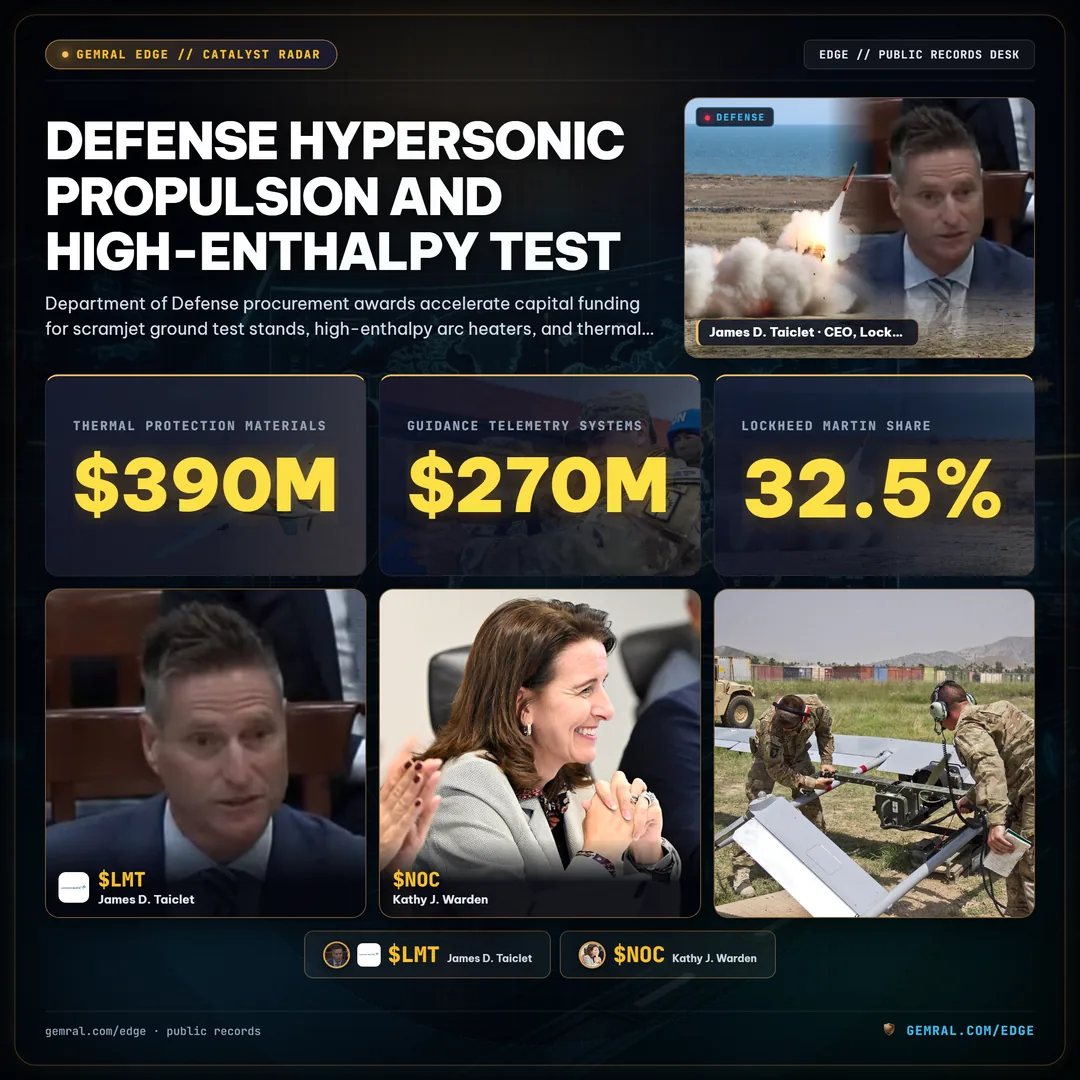
The race for hypersonic operational deployment has shifted decisively from theoretical aerodynamic modeling to industrial-scale ground testing and propulsion production. In mid-September 2026, Department of Defense procurement notices and contract digest modifications confirmed an accelerated wave of capital awards directed at high-enthalpy arc heaters, scramjet test stands, and thermal protection manufacturing lines. With annualized testing obligations projected to reach $2.35 billion for fiscal year 2026, defense procurement records reveal that the primary bottleneck in fielding Mach 5+ strike and defense platforms is no longer airframe geometry, but ground simulation capacity under severe aerothermal heating conditions.
1. Ground Testing Bottlenecks and High-Enthalpy Infrastructure Mandates
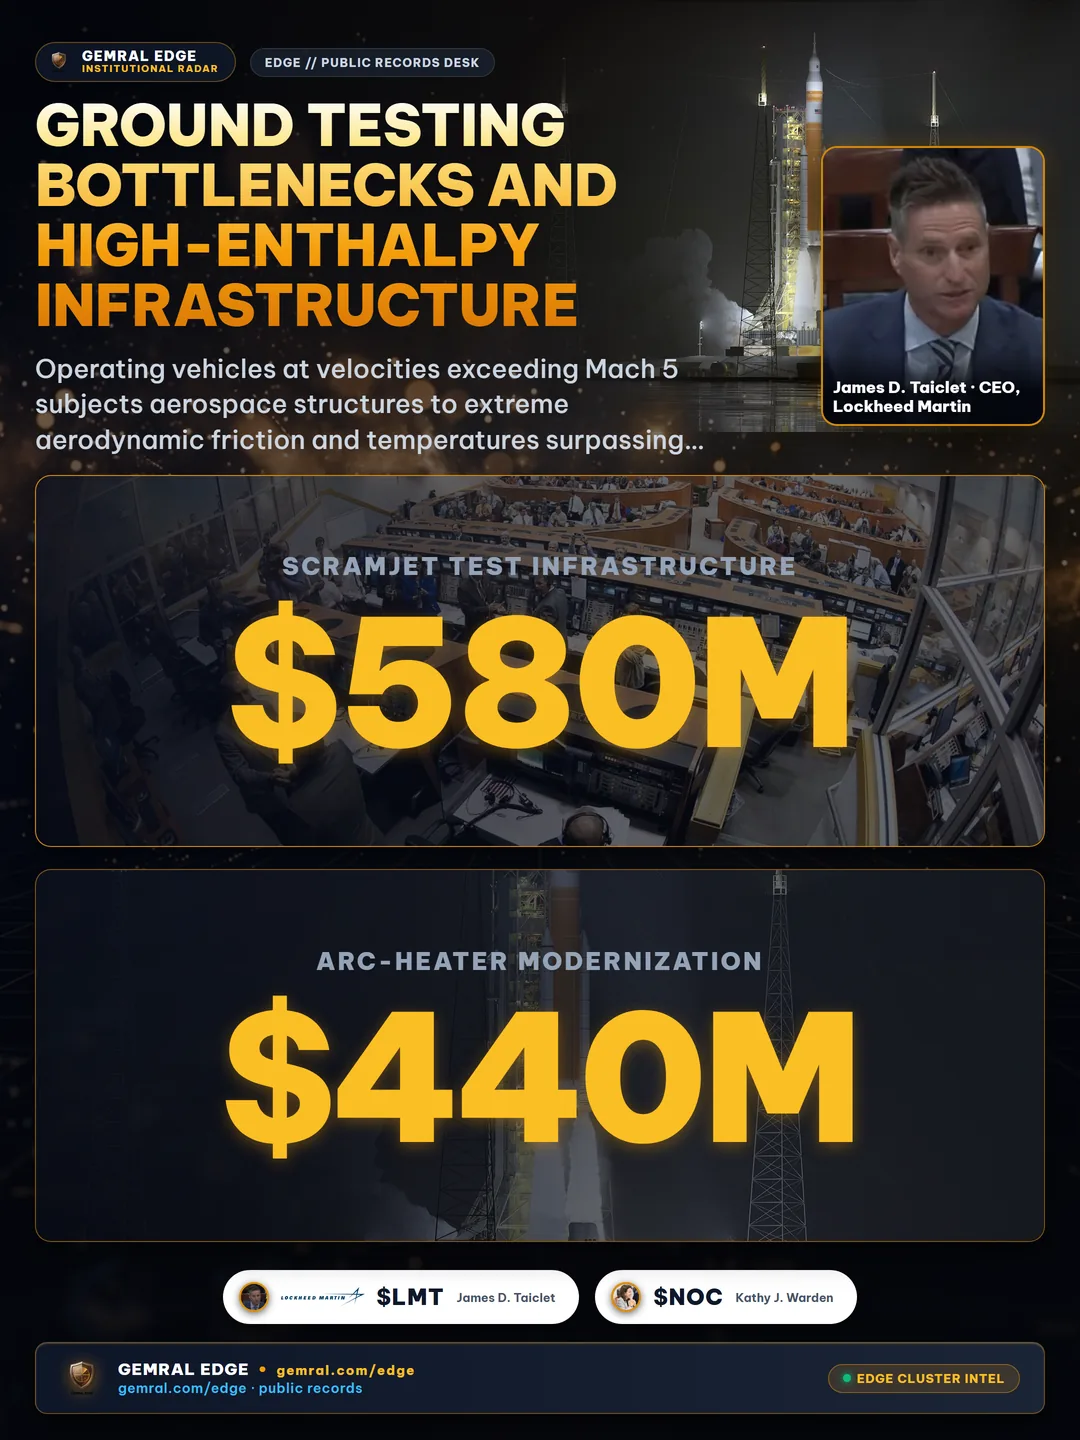
Operating vehicles at velocities exceeding Mach 5 subjects aerospace structures to extreme aerodynamic friction and temperatures surpassing 3,000 degrees Fahrenheit. Before an air-breathing scramjet or hypersonic glide vehicle can undertake live range flight tests over oceanic corridors, it requires hundreds of hours of ground characterization in specialized high-enthalpy wind tunnels and arc-heater test facilities. These specialized complexes recreate true flight enthalpy, stagnation pressure, and chemical dissociation of atmospheric gas mixtures.
Throughout the past three fiscal cycles, limited ground test throughput formed the critical path constraint for United States strike initiatives. In response, Pentagon acquisition leaders structured a series of targeted infrastructure modernization awards to expand the physical availability of Mach 5 to Mach 10 testing facilities.
As illustrated in Figure 1, the largest individual tranche of FY2026 funding—totaling $580 million—is committed directly to scramjet propulsion test infrastructure and dynamic fuel injection test benches. High-enthalpy arc-heater modernization secured $440 million in capital awards, while carbon-carbon composite thermal protection materials received $390 million and high-temperature guidance telemetry systems captured $270 million in obligated funding. This structural distribution underscores that federal spending is actively resolving component qualification backlogs prior to high-cadence flight demonstrations.
2. Prime Contractor Market Concentration and Supply Chain Architecture
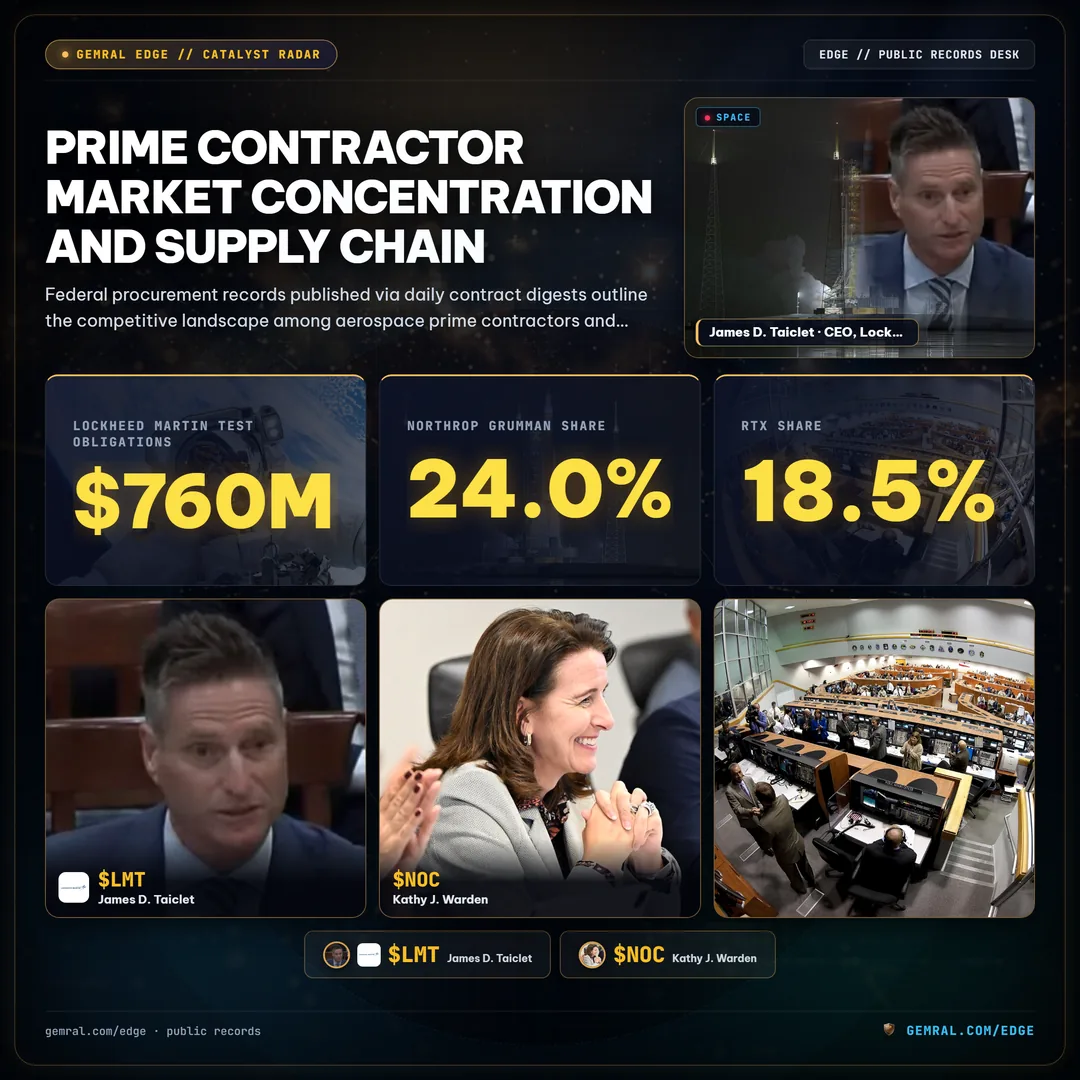
Federal procurement records published via daily contract digests outline the competitive landscape among aerospace prime contractors and specialized research entities. Unlike conventional aircraft acquisition, hypersonic ground test and propulsion manufacturing requires bespoke industrial facilities, specialized vacuum chambers, and high-megawatt power substations capable of driving continuous arc-heater operations.
Analysis of transaction-level award data reveals a concentrated prime contractor hierarchy managing high-enthalpy development programs:
- Lockheed Martin (32.5% Market Share): Serving as the prime integrator for major boost-glide and tactical hypersonic weapon architectures, holding $760 million in active ground testing and system integration contract obligations.
- Northrop Grumman (24.0% Market Share): Leading specialized scramjet combustor manufacturing and advanced solid rocket motor stage testing across modernized ground facilities in Maryland and Utah.
- Raytheon / RTX (18.5% Market Share): Capturing $435 million in subsystem testing contracts, focusing on seeker durability, high-temperature radio frequency radomes, and sensor window cooling technologies.
- Aerojet Rocketdyne (14.0% Market Share): Anchoring domestic scramjet propulsion production and high-pressure dual-mode ramjet test stand operations.
- University Laboratories & Specialized Testing Centers (11.0% Market Share): Universities possessing Mach 6 quiet wind tunnels and specialized aerothermal shock tubes, providing academic verification for boundary layer transition models.
The capital commitments awarded in September 2026 emphasize long-lead manufacturing equipment and automated tape placement systems for carbon-carbon composite leading edges. By establishing domestic high-temperature component lines, prime defense contractors are transitioning from custom prototype fabrication to repeatable serial production batches.
3. Obligation Velocity: Tracking the Multi-Year Capex Surge
Tracking the annual obligation velocity provides institutional investors and defense analysts with a quantitative measure of program priority. When public procurement programs expand their capital spending on physical test infrastructure, it serves as a reliable leading indicator for forthcoming production quantity determinations.
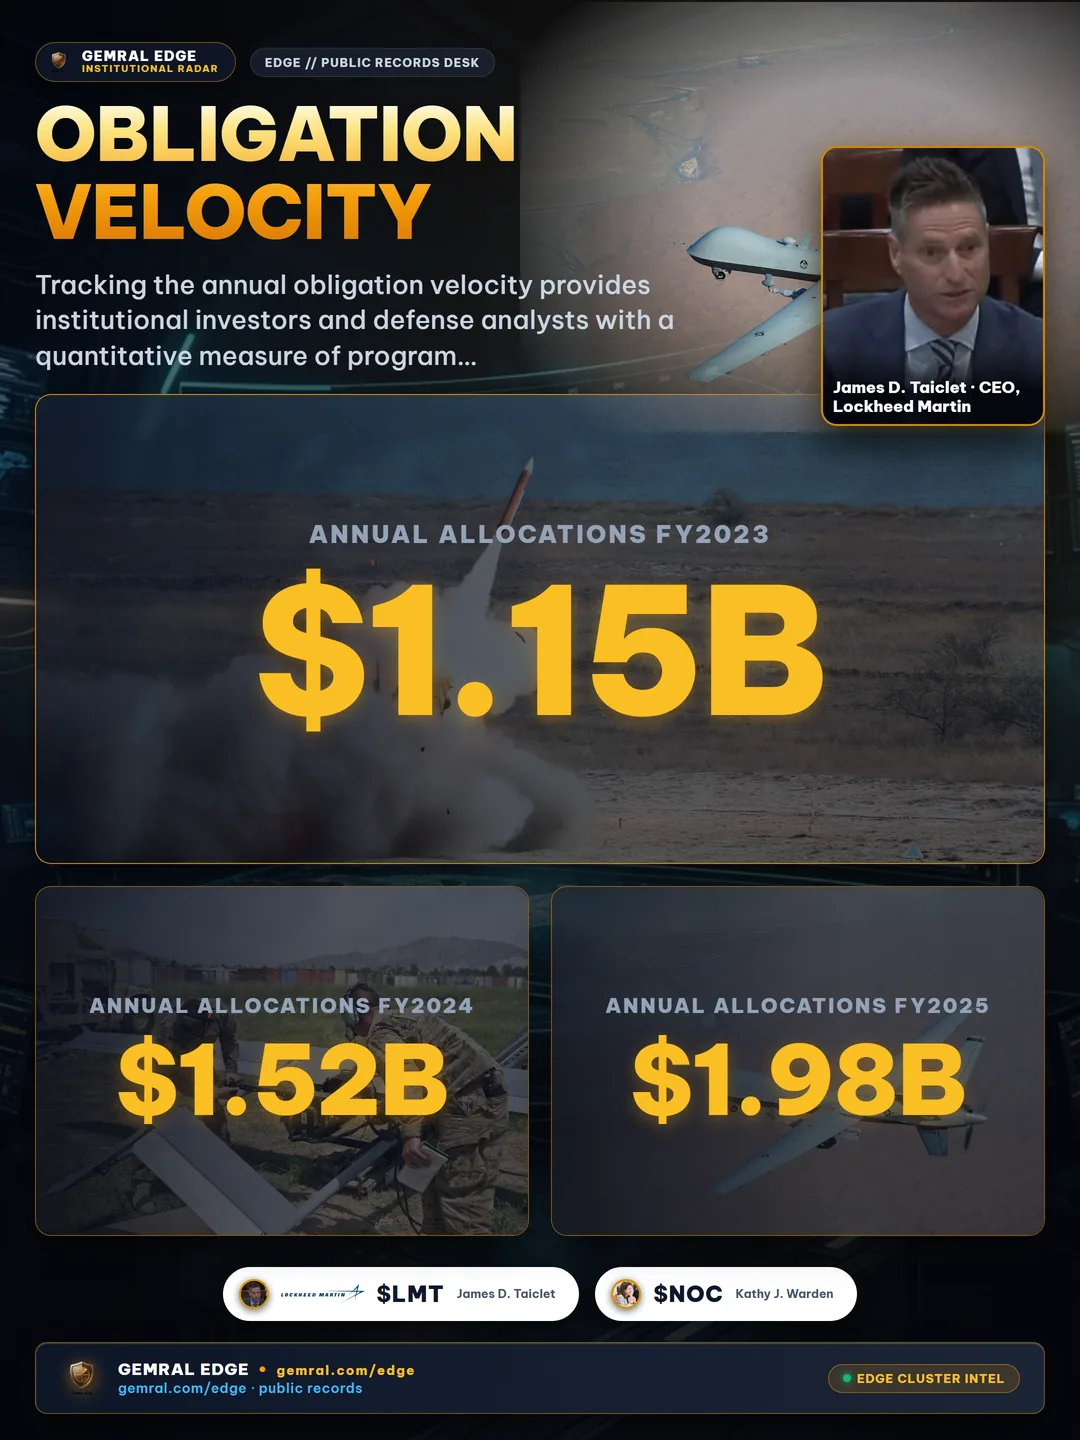
Department of Defense budgetary records demonstrate a steep expansion trajectory in ground testing and flight readiness obligations across the FY2023 through FY2026 timeline. Total annual allocations rose from $1.15 billion in FY2023 to $1.52 billion in FY2024, reaching $1.98 billion in FY2025 before accelerating toward an estimated $2.35 billion in FY2026.
This multi-year capital surge reflects a strategic doctrine shift. In earlier stages of development, limited test assets forced program managers to space flight trials months apart. A single anomaly during a live flight trial often halted testing for over a year while root cause analysis was conducted. By deploying over $2.35 billion into ground-based high-enthalpy simulation stands, flight vehicle designs can undergo thousands of simulated flight cycles indoors, eliminating design flaws before hardware reaches sea ranges.
4. Ground Test Capacity Expansion: Measuring Operational Throughput
The definitive operational metric measuring the return on federal infrastructure capital is annual test hours available across national facilities. According to technical reports released by the Arnold Engineering Development Complex (AEDC) and associated naval research facilities, available testing hours in Mach 5 to Mach 10 simulation tunnels have expanded dramatically since 2023.
In 2023, national aerothermal test facilities provided 620 operational hours, leaving multi-month scheduling backlogs for operational military programs. Through the commissioning of upgraded high-pressure air reservoirs, multi-megawatt arc-heater power upgrades, and automated data acquisition architectures, operational testing capacity climbed to 890 hours in 2024, 1,240 hours in 2025, and reached 1,680 hours in 2026. Projections for 2027 establish an operational throughput target of 2,050 annual testing hours.
The expansion to 1,680 hours in 2026 represents a 170% capacity increase relative to 2023 baselines. This throughput expansion allows engineering teams to perform continuous aerothermal testing on thermal protection coatings, seeker windows, and scramjet inlet boundary layers, directly shortening vehicle iteration timelines from months to days.
5. Strategic Outlook for Defense Procurement and Industrial Base Scaling
The contract awards finalized in September 2026 mark a decisive turning point in United States defense technology posture. For institutional observers analyzing aerospace supply chains, several structural shifts are readily apparent:
- Transition from R&D to Procurement: The concentration of awards in high-throughput ground infrastructure signals that prototype designs are freezing. Once ground test hours validate vehicle durability, contract structures typically shift toward low-rate initial production (LRIP) authorizations.
- Dual-Use Propulsion Industrial Expansion: Capital grants allocated toward high-temperature materials and advanced combustion nozzles create durable supply chain capabilities that extend beyond strike weapons into commercial high-speed transport and orbital space launch architectures.
- Multi-Year Backlog Stability: Tier-1 and Tier-2 defense suppliers with specialized composite tape-laying machinery, high-temperature radome manufacturing capacity, and vacuum test cells possess multi-year order backlogs that remain insulated from broad commercial economic cycles.
By reading the granular public records of defense contract digests, capital market participants can observe technology inflection points quarters before commercial hardware debuts. The rapid scaling of high-enthalpy testing stands is not merely an engineering milestone; it is the physical foundation enabling scalable defense deployment through the remainder of the decade.
Empirical Intelligence & Catalyst Radars:
• Federal Defense Procurement: Search live Pentagon prime awards and hypersonic propulsion contracts on the Federal Contracts & War Chest Radar.
• Pre-Award Defense Pipeline: Discover prototype OTA test stand solicitations and aerospace cluster awards on the DEEP FLOW Institutional Radar.
• Prototype Defense Events: Track ongoing DoD Other Transaction Authority (OTA) test stand milestones on the DoD Prototype OTA Pre-Award Contract Horizon.
Track Federal Defense Procurement Telemetry
Monitor real-time federal award flows, contractor obligation velocity, and aerospace procurement clusters across global markets with the analytics platform.
Explore the Gemral Edge Procurement Terminal →